Weekly recap: the biggest week we have measured, closing the biggest month
Attributed stablecoin volume was $22.08M, an all-time high, up 7.7%. It closes August at $83.89M — a record month, up 22.1% on July, with record deposits and record wallets. Thirteen of nineteen venues grew. The series is restated: four venues whose business and personal flow share one rail now report total flow rather than the retail size band.
- $22.08M
- This week
- $83.89M
- August
- 51,698
- Active wallets
- 13 of 19
- Venues that grew
up 7.7%, an all-time high
up 22.1%, a record month
an all-time high
six last week
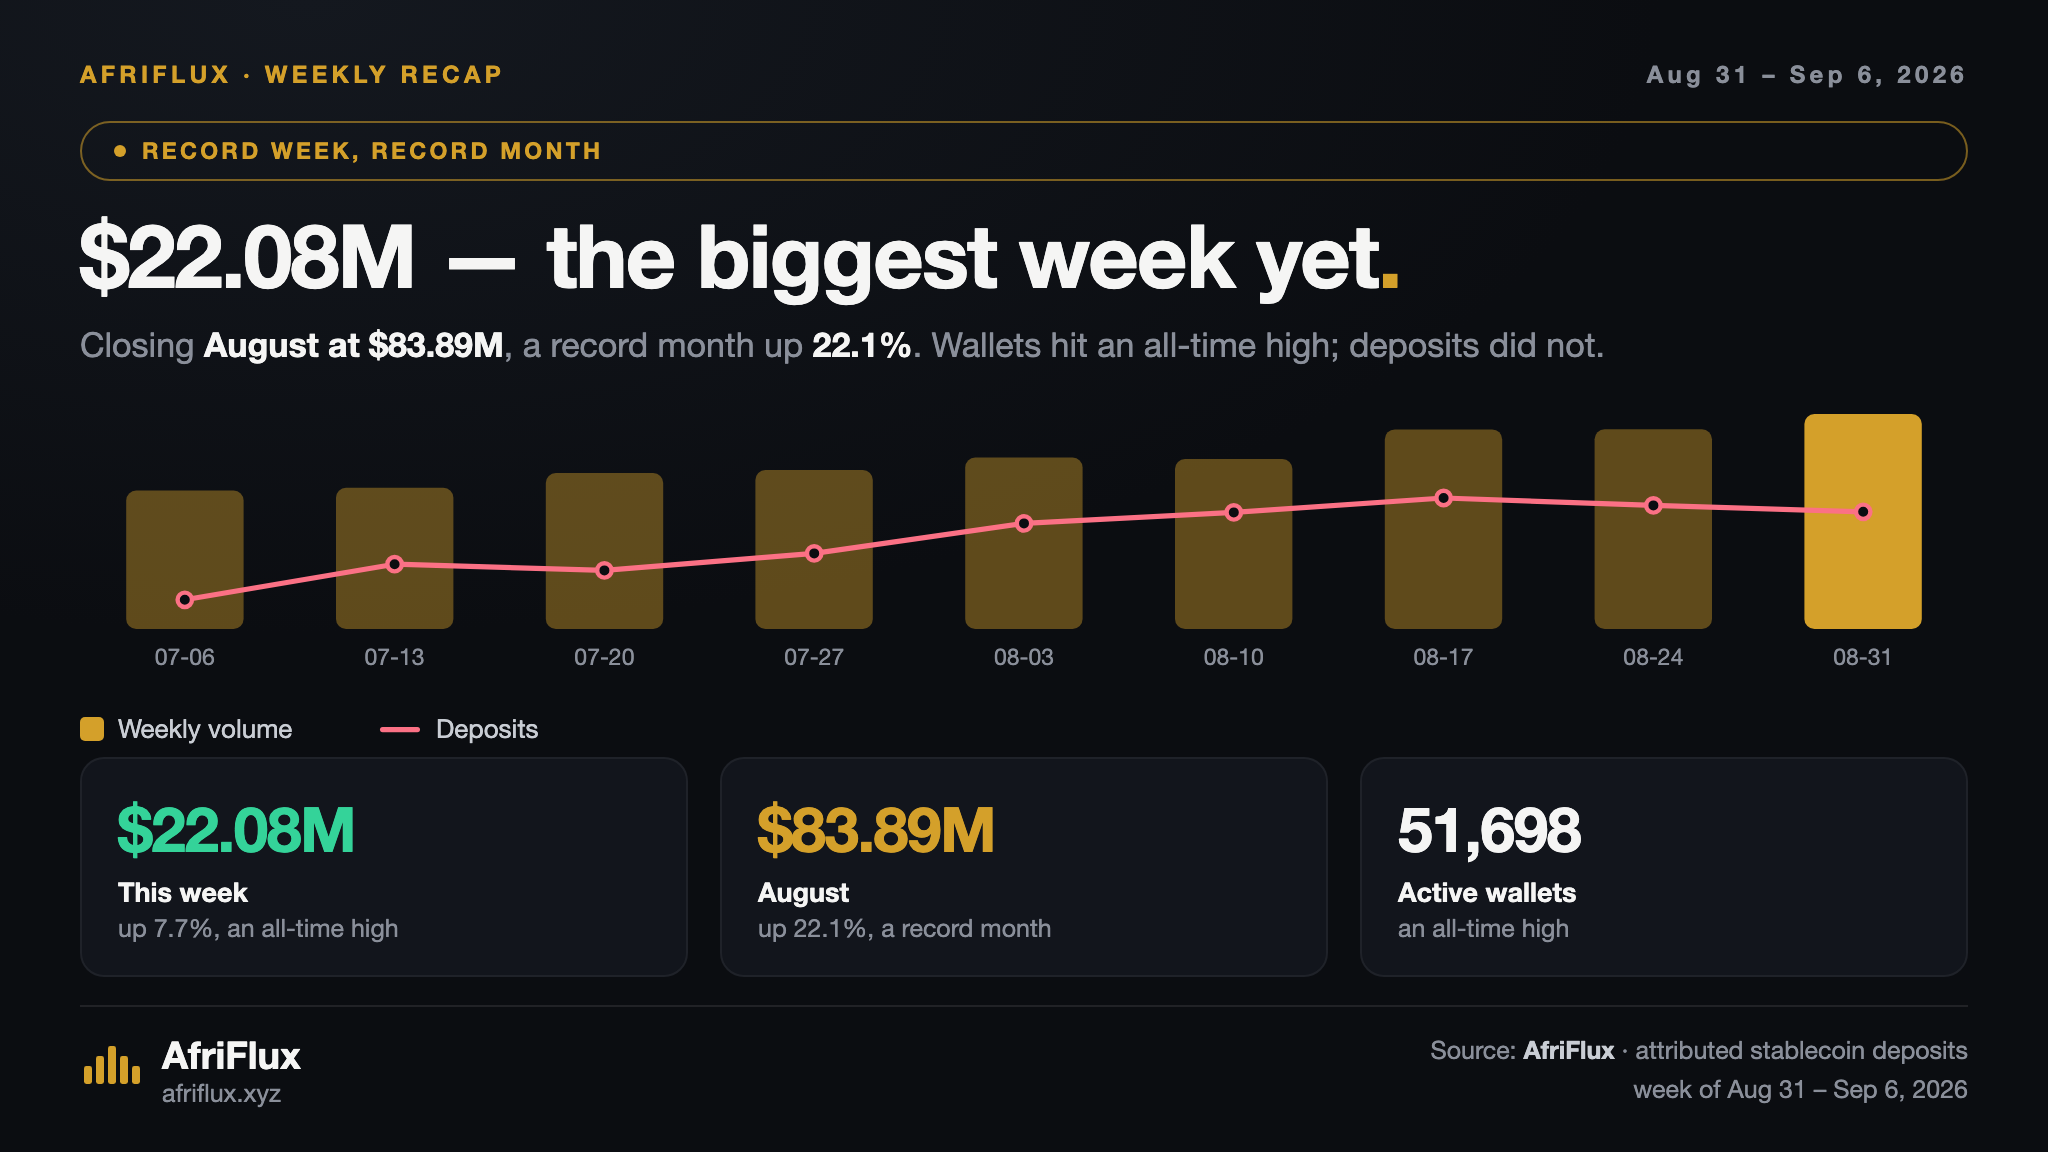
Attributed stablecoin volume across the 19 venues we track was $22,075,305 in the week of 31 August to 6 September. That is the largest week in 331 weeks of coverage, up 7.7%.
It closes the largest month.
August: $83,885,218
Up 22.1% on July's $68,689,824. A record, and not a narrow one — records on all three measures at once:
| August | July | ||
|---|---|---|---|
| Volume | $83,885,218 | $68,689,824 | +22.1% |
| Deposits | 683,565 | 581,508 | +17.6% |
| Active wallets | 112,405 | 108,957 | +3.2% |
Volume grew six times faster than the wallet count. August was a month in which the people already here moved more, rather than a month in which many more people arrived.
What drove it
Quidax added 33.7% to $20,931,174 — the single largest contribution to August's rise. Chipper did $3,970,232, up 98.5%, and did it by moving onto Solana. Daya Pro did $6,196,281, up 194.7%, on 86 wallets for the whole month.
Spenda grew 18.5% to $11,718,388 and again recorded more deposits than any other venue — 326,382 of them, from 57,682 wallets. Nobody else is close on participation.
And Monica's seventeen-month growth streak ended: down 2.9% to $17,099,505. Its active wallets rose 9.0% while volume per wallet fell 11.0%. More people, each doing less — the mirror image of the market around it.
Falling in August: Roqqu −31.0%, Azza −31.1%, Accrue −49.6%.
The week itself
$22,075,305, up 7.7% from a restated $20,505,846.
Active wallets hit 51,698 — an all-time high. Deposits were 154,316, below the 159,144 recorded on 17 August. The average deposit rose from $121 to $143.
Thirteen of nineteen venues grew, against six last week. This was a broad week, not a concentrated one.
Quidax $5,505,085 (+9.0%), Monica $4,673,677 (+10.8%), Spenda $2,848,971 (−2.4%), Daya Pro $2,229,296 (+10.5%), Grey Finance $1,944,981 (+42.9%).
Daya Pro has now held its new level for three weeks — $2.81M, $2.02M, $2.23M, against a nine-week average of $447,000 before that. On 41 wallets. We called it a possible one-week event a fortnight ago and revised that last Monday; three weeks in, the revision stands.
The series has been restated, again
Four venues — Onboard, Grey Finance, Accrue and Raenest — run business and personal flow on the same rails. From this issue we report their total observed flow rather than the retail size band. The full reasoning is here, and it changes the week of 24 August from the $18.96M we published to $20.51M.
It also removes a number we would otherwise have printed. On the old basis Onboard appeared to grow 539% this week. On the corrected basis it fell 22.7% — its total flow went from $1,241,023 to $959,122, and all that actually changed was how much of it landed inside a size band.
The native layer had a record too, and it means less than it looks
Transfer volume across native African stablecoins was $19,036,705, up 215.4%, on 21,035 transfers. cNGN was $18,851,802 of it, up 237%, and Base carried $12,490,118 of that, up 606%.
Seventy transfers — 0.4% of the 16,535 on Base — account for 56.7% of that volume. They are one cluster: freshly minted cNGN walked through five or six hops into a yield vault that is HyperFX solver inventory, with every hop counted in full.
We have written it up separately, because it is the clearest example yet of why we do not treat transfer volume as a usage measure.
Elsewhere in native: cKES fell 99.3% to $1,877 and cZAR to $5, from $254,754 and $149,591. We excluded both from last week's issue on the grounds that a handful of transfers on a $1-average base is not a trend. It was not.
Method
Attributed stablecoin deposit volume across the 19 venues in AfriFlux coverage, for the ISO week of 31 August – 6 September 2026 and the calendar month of August 2026. Deposit-side only — excludes withdrawals, transfers between venue-controlled addresses, and all off-chain activity. From this issue, the four venues tagged not_separable (Onboard, Grey Finance, Accrue, Raenest) report total observed flow rather than the retail size band, because their business and personal books share one rail and cannot be separated on-chain; the other fifteen are unchanged. That restates the series: the week of 24 August now reads $20,505,846 against the $18,955,618 published on 31 August, of which $1,505,164 is the treatment change and $45,065 is ordinary attribution drift. August reads $83,885,218 against $78,619,725 on the old basis. All rankings are measured against the restated series. Native stablecoin figures are transfer volume only and exclude mints and burns.
How attribution works →Cite this
Free to cite with attribution. No embargo, no approval needed.
AfriFlux (2026). Weekly recap: the biggest week we have measured, closing the biggest month. Published 7 September 2026. https://www.afriflux.xyz/feed/weekly-recap-2026-w36
Reproducing a chart? Use this line: Source: AfriFlux — on-chain intelligence for Africa's stablecoin economy. afriflux.xyz