Weekly recap: a down week inside a month running ahead of August
Attributed stablecoin volume was $18.34M, down 16.9% from a record week. The fall was broad — excluding Daya Pro the market still fell 11.9% — but September's first thirteen days are running 11.1% ahead of August's, the record month. Spenda set a deposit record and active wallets held within 59 of their high.
- $18.34M
- This week
- +11.1%
- September so far
- 51,734
- Active wallets
- 6 of 19
- Venues that grew
down 16.9%, fourth-largest
vs August's first 13 days
59 below last week's record
thirteen fell
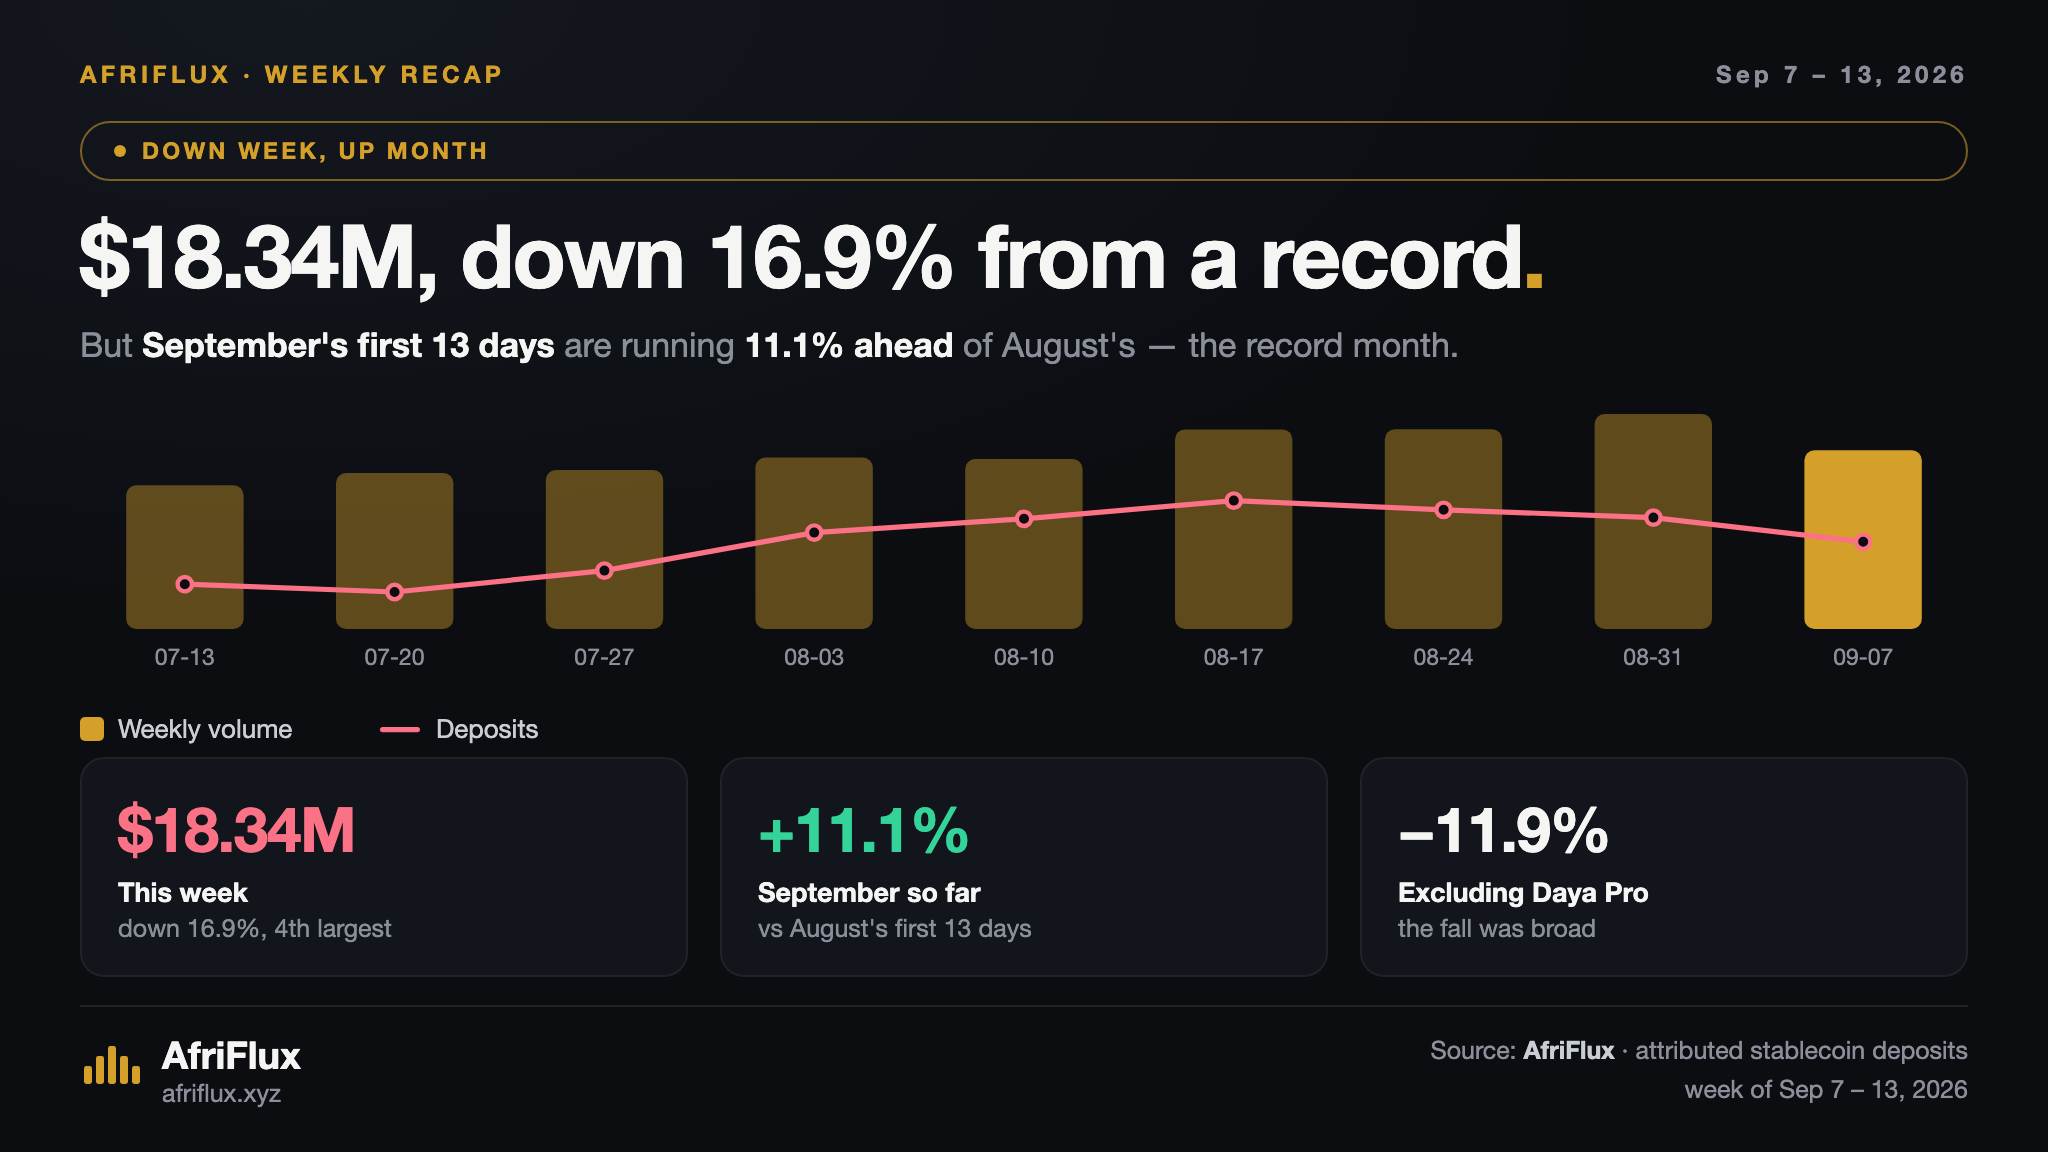
Attributed stablecoin volume across the 19 venues we track was $18,339,619 in the week of 7 to 13 September — down 16.9% from last week's record of $22,069,641, and the fourth-largest week we have measured.
Read on its own, that is a bad week. Read against the month, it is not.
September is running ahead of the record month
The first thirteen days of September did $36,465,292. The first thirteen days of August — the largest month in our coverage — did $32,813,107.
September is running 11.1% ahead, on almost exactly the same number of deposits: 280,694 against 279,710.
So the week gave back part of a spike. It did not break the trend.
The fall was broad
Six of nineteen venues grew. Thirteen fell.
Daya Pro fell 61.5% and accounts for $1,371,800 of the $3,730,022 decline — 36.8% of it. But strip Daya Pro out and the rest of the market still fell 11.9%. This was not one venue.
Quidax $4,741,445 (−13.7%), Monica $4,100,404 (−12.3%), Spenda $2,774,575 (−2.6%), Grey Finance $1,518,947 (−21.9%), Busha $933,150 (−16.6%), Onboard $644,818 (−32.8%).
Growing: Chipper +27.5% to $1,041,917, and Roqqu +9.7% to $292,874.
Participation held while volume fell
Active wallets were 51,734 — within 59 of last week's record 51,793. Deposits fell to 147,707, the fewest in six weeks, and the average deposit came down from $143 to $124.
The same people were there. They moved less.
Spenda is the clearest case: its volume fell 2.6% while it recorded 78,257 deposits, the most any venue has ever done in a week. More here.
Two calls from last week, resolved
Daya Pro fell back — but not all the way. At $857,496 it is still 1.9 times its pre-August average of $447,000. Here is what that means for what we said.
Solana lost the neobank lead. We said on 7 September that its $93,163 margin over BNB Chain was fragile and that we would report a reversal. Through 13 September, BNB Chain is back ahead.
cNGN: fewer dollars, more people
cNGN transfer volume fell 25.1% to $14,121,361. On Base it fell 28.8% to $8,896,556 — while daily active addresses rose 65% to 962, the highest we have recorded.
That is the second week running in which cNGN's volume and its users moved in opposite directions. We think that is now the finding.
Elsewhere in native: ZARP rose to $370,701, but $335,382 of it landed on a single day across 106 transfers. We are not reading a trend into it.
Infrastructure
HyperFX settled $909,234 across 88 fills, down 38.0% from its record week. Its last two weeks together are 74.6% of everything it has ever settled. Textile FX cleared $1,593,180 in African notional, down 15.0%, on BNB Chain and Celo. Paycrest settled $409,923, up 40.7%, across 716 orders.
None of this is added to market volume.
Method
Attributed stablecoin deposit volume across the 19 venues in AfriFlux coverage for the ISO week of 7–13 September 2026. Deposit-side only — excludes withdrawals, transfers between venue-controlled addresses, and all off-chain activity. The four venues tagged not_separable (Onboard, Grey Finance, Accrue, Raenest) report total observed flow; the other fifteen report the retail size band. The week of 31 August, published on 7 September at $22,075,305, now reads $22,069,641, a 0.03% restatement from ordinary attribution drift. The September comparison sums daily figures for 1–13 September against 1–13 August on the same basis. Native stablecoin figures are transfer volume only and exclude mints and burns; infrastructure volume is measured separately and never added to market volume.
How attribution works →Cite this
Free to cite with attribution. No embargo, no approval needed.
AfriFlux (2026). Weekly recap: a down week inside a month running ahead of August. Published 14 September 2026. https://www.afriflux.xyz/feed/weekly-recap-2026-w37
Reproducing a chart? Use this line: Source: AfriFlux — on-chain intelligence for Africa's stablecoin economy. afriflux.xyz